Pledging collateral is not just a requirement for securing an FHLBank Boston advance. It is part of the liquidity infrastructure of the balance sheet. In this case study, Senior Sales & Strategies Specialist Tyler Buckeridge provides information about optimizing collateral.
August 2026 Peer Analysis and Balance Sheet Strategies Update
FHLBank Boston’s strategies team discusses what is occurring on depository member balance sheets and reviews important trends in the capital markets, economy, and banking industry.
Case Study: Identifying Value in Short-Term Floating-Rate Funding
This case study demonstrates that rolling short-term borrowings should not automatically default to traditional fixed-rate renewals. By understanding repricing risk, breakeven points, and funding objectives, institutions can make more informed and cost-effective funding decisions.
In addition to selling new production loans through the Mortgage Partnership Finance® (MPF®) Program, selling seasoned loans can be a useful tool to navigate different risks and adjust the composition of both the asset and liability sides of the balance sheet.
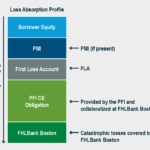
The MPF Program uses a layered credit enhancement structure in which losses are absorbed sequentially by borrower equity, private mortgage insurance (if applicable), the First Loss Account, the PFI’s Credit Enhancement Obligation, and finally FHLBank Boston.
This case study examines whether newly originated residential mortgages should be held in portfolio or sold through the Mortgage Partnership Finance® (MPF®) 35 Program, emphasizing that a mortgage’s coupon rate alone does not determine its value. Using a sample $10 million mortgage pool, the analysis found that selling through MPF 35 and redeploying the proceeds generated significantly greater five-year economic value than holding the loans, while also transferring interest rate and prepayment risk.
Our Annual Report illustrates how the Bank’s steady financial performance and member partnerships are advancing New England’s economy and enabling us to fulfill our mission each day.